Much of the ESG data is contained in contracts: the share of renewable energy in an energy contract, social standards in a supplier contract, and data protection obligations in a cloud contract. By systematically recording these clauses, you can substantiate ESG metrics without having to search through PDFs every year. This article explains what ESG reporting is, what obligations apply today under the CSRD, and what contract data you need for this purpose.
What is ESG reporting?
In recent years, sustainability has evolved from a marginal issue to a key management area in business and society. The adoption of the United Nations Sustainable Development Goals (SDGs) made it clear that economic, environmental, and social aspects must be considered together. In this context, ESG— environment, social, and governance —has established itself as a framework for measuring the impact of companies in these three areas.
As part of sustainability reporting, ESG reporting is the process by which companies systematically record, evaluate, and disclose their performance and risks in relation to environmental, social, and responsible corporate governance issues . This involves more than just complying with regulatory requirements: ESG reporting influences reputation and access to capital and shapes the expectations of customers, employees, and investors. Good ESG reporting shows how business activities impact the environment and society, how governance structures are set up, and what financial consequences this may have. It thus forms the basis for strategic decisions.
The three dimensions: Environment, Social, and Governance
In terms of content, ESG reporting is structured along the three dimensions of E, S, and G. In the area of Environment ( ), the focus is on topics such as climate change, emissions, energy consumption, resource use, and the circular economy. Social encompasses working conditions, equality, supply chain responsibility, affected local groups, and dealings with customers and end consumers, among other things. Governance addresses issues of corporate management, from the composition of management bodies and corruption prevention to compliance and internal control systems.
Before addressing the question of what role contracts play in this context, it is therefore crucial to understand the requirements set out in the regulatory framework, in particular by CSRD, ESRS, and EU taxonomy, and how good ESG reporting is structured in terms of content. Only then can it be determined what data companies actually need to provide and why contract information will later become such a central database.
CSRD, ESRS & Co.: What ESG reporting requirements apply to European companies?
With the Corporate Sustainability Reporting Directive (CSRD), the European Commission has created the framework for significantly more comprehensive and binding sustainability reporting in the EU. The directive replaces the previous Non-Financial Reporting Directive (NFRD) and expands both the scope of the reports and the group of companies affected.
Who is subject to the sustainability reporting rules?
The CSRD has been amended several times. First, the 2025 “Stop-the-Clock” Directive postponed the obligations for the second and third waves by two years. With the Omnibus I package, the EU significantly narrowed the scope of entities subject to the requirements in early 2026: Only companies with more than 1,000 employees and revenue exceeding €450 million are now required to report. For large companies that were not previously subject to the NFRD, the requirement takes effect starting with the 2027 fiscal year, and the first report is due in 2028. The ESRS requirements have been significantly reduced. (As of February 2026)
For CFOs, legal departments, and ESG officers, this means that many small and medium-sized enterprises are no longer directly subject to the CSRD. However, banks, investors, and large customers continue to request ESG data, often through the supply chain. Much of this data is contained in contracts.
ESRS: What specifically do companies have to disclose?
The CSRD stipulates that companies must report if they European Sustainability Reporting Standards (ESRS) specify in detail what must be disclosed. Companies subject to the CSRD must align their ESG reporting structure with these standards. The ESRS are developed by the European Financial Reporting Advisory Group (EFRAG) on behalf of the European Commission. They consist of:
- General standards: define basic principles, report structure, and double materiality.
- ESG issue standards: define specific requirements relating to environmental, social, and governance issues (e.g., climate, resources, working conditions, human rights, compliance).
- Industry-specific standards (planned): supplement typical risks, key figures, and reporting requirements for each industry.
In practice, this means that ESG reporting will become more metrics-driven. Companies will not only have to provide qualitative descriptions, but also a large number of data points on emissions, energy consumption, supply chains, and governance structures, among other things. This also includes clear derivations, assumptions, and internal control mechanisms.
This is where the link to the world of contracts comes in: a significant portion of this information is anchored in agreements with customers, suppliers, energy providers, or financial partners and must be identified, structured, and made verifiable for ESRS-compliant reporting.
EU taxonomy and global frameworks: important context, not competition
In addition to the CSRD and the ESRS, the EU taxonomy plays a central role. It defines which economic activities are considered environmentally sustainable, thereby creating a common frame of reference for companies and financial market players. The aim is to avoid greenwashing and channel capital specifically into sustainable activities.
Investors and analysts also often refer to global frameworks such as the Global Reporting Initiative (GRI) and the standards of the International Sustainability Standards Board (ISSB); in the financial sector, disclosure requirements such as the Sustainable Finance Disclosure Regulation (SFDR) also play an important role. These frameworks do not conflict with CSRD and ESRS, but rather form a reference framework that many capital market participants worldwide use for guidance.
However, for companies in Germany and the EU, the following is crucial: CSRD, ESRS, and EU taxonomy form the binding core of sustainability reporting in the European legal area—with clear requirements for data quality, governance, and verifiability. Everything else is helpful context, but it is no substitute for consistently aligning your own processes and data streams with these requirements.
What makes for good ESG reporting?
Contemporary ESG reporting goes far beyond a loose collection of key figures. At its core, it is about consistently presenting a company's sustainability performance: How does the business model affect the environment and society, which governance structures control this impact, and what risks and financial implications arise from it? A good report combines qualitative assessment with clear, comprehensible key figures and shows how sustainability is anchored in strategy, management, and everyday operations.
This usually includes a description of the business model and the key ESG issues that are particularly relevant to the company and its stakeholders. This materiality analysis forms the basis for explaining environmental, social, and governance goals and measures in a comprehensible manner. It is supplemented by key figures such as energy consumption, emissions, labor and supply chain standards, and information on the role of the executive board and supervisory bodies in corporate governance. In addition, there is a description of how the underlying data is collected, verified, and internally controlled.
The principle of double materiality is crucial here: ESG aspects are assessed both in terms of the impact the company has on the environment and society, and in terms of the financial effects ESG issues can have on the company itself. ESG reporting is therefore not purely a communication exercise, but part of governance and risk management.
What role do contracts play in ESG reporting?
Many ESG targets are written into strategy papers and presentations, but they only become effective when they are legally binding: in contracts. Energy contracts, for example, specify whether and to what extent electricity is sourced from renewable sources or what efficiency requirements apply. Supplier contracts define social and environmental standards, audit rights, or requirements for subcontractors. SaaS and cloud contracts contain specifications on information security, data protection, and other governance issues.
For robust ESG reporting, these contractually agreed obligations must be identified and prepared in such a way that they are reflected in the report. Contract data can be used to determine how deeply sustainability is already anchored in procurement, the supply chain, the IT landscape, and financing, and where gaps still exist. In practice, however, contracts are often spread across different files and ESG-relevant clauses are not recorded in a structured manner. The first step is therefore often to bring clarity and structure to the contract portfolio before the content can be meaningfully integrated into sustainability reporting.
From sourcing to contract fulfillment: Where does ESG fit into the contract lifecycle?
ESG does not begin with the finished report, but much earlier – during sourcing and negotiations. Data is generated throughout the entire contract lifecycle, which should later be referenced in ESG reporting.
Pre-Award: ESG in sourcing and tenders
Many companies already define ESG criteria intheir tenders: suppliers are evaluated according to environmental and social standards, proof of certifications or climate targets is requested, and ESG indicators are included in scoring systems. This shifts ESG from an "add-on" to a regular component of award and decision-making processes.
At-Award: ESG in clauses and KPIs
These requirements become concrete in the contract phase: ESG criteria are translated into clauses and performance indicators, for example in the form of emission targets, energy consumption specifications, mandatory training, documentation requirements, or sanctions for violations. This is where it is decided how measurable and enforceable ESG requirements actually are in everyday operations.
Post-Award: Obligations, Risks, Monitoring
Once the contract is signed, the focus shifts to monitoring obligations and risks. It must be possible to verify whether agreed-upon ESG reports were submitted on time, whether certificates are up to date, or whether there are any anomalies in specific supply chains. A modern Contract Management system supports business units and management in not only storing this information but also actively managing it. This is achieved, for example, through tasks, reminders, analyses, and interfaces to ESG reporting and financial systems.
What specific data from contracts is required for ESG reporting?
In order for contract information to be usable in ESG reporting, it must be recorded in a structured manner . In the environmental area, for example, it may be relevant whether energy contracts specify the share of renewable energy, what emission targets have been agreed upon, or what regulations apply to waste, recycling, and resource use. Such information can be mapped as fields and attributes in the Contract Management and later used in analyses.
In the social sphere, contractual clauses on labor and social standards, compliance with human rights in the supply chain, health and security requirements, and training and documentation obligations are important. At the governance level, regulations on anti-corruption, whistleblower systems, data protection, information security, and data processing agreements play a role. If this content is available not only in the body text of individual PDFs but also as structured data points, ESG reports can be created much more efficiently and the risk of overlooking key obligations is reduced.
Bond management: Why contractual obligations are crucial for ESG reporting
ESG clauses in contracts are only effective if their fulfillment is also monitored. This is precisely where obligation management comes in: it involvessystematically recording contractual obligations, translating them into actionable tasks, and tracking compliance. For ESG, this means, for example, not only being aware of regular reports to customers or investors, agreed audits on social and environmental standards, evidence of certificates, or the achievement of certain emission or energy targets, but also actively managing them.
Digital contract management systems ( Contract Management) such as ContractHero help identify these obligations within the contract text, assign responsible parties, and monitor deadlines . For example , through AI-powered search and clause recognition, customizable fields, task and responsibility assignment, as well as automatic reminders and deadline calendars. In this way, a static document is transformed into a management tool: ESG information is no longer merely contained within the contract but is integrated into processes and reporting via Obligation Management. For ESG reporting, this means significantly greater reliability, as up-to-date and verified information from contracts is systematically incorporated into the reporting.
How do CLM systems provide technical support for ESG reporting?
Contract lifecycle management (CLM) systems and specialized ESG reporting solutions are increasingly converging. While ESG tools are designed to prepare data from different sources in a manner that complies with CSRD and ESRS requirements, CLM systems provide an essential component: the structured contract information on which many ESG metrics are based.
A modern CLM system should consolidate contracts from relevant source systems such as ERP, HR, or purchasing, provide ESG-relevant fields, and enable existing contracts to be searched for specific clauses. In addition, interfaces are important for exchanging contract data with ESG reporting and financial systems. Especially in highly regulated industries such as financial services or insurance, where extensive information on credit portfolios, investments, and supply chains is required, it is almost impossible to manage the amount of data needed for reporting without automation.
Which ESG clauses should be included in contracts?
The table shows typical contract types, the ESG clauses they contain, and the field in which you enter the information in the Contract Management .
In ContractHero, you create these fields for each contract type. The AI analysis extracts much of the information directly from the contract; all you have to do is review it. Set up reminders before a certificate or proof of compliance expires.
Recommendations for CFOs, legal, and ESG officers
Companies are faced with the task of establishing robust ESG reporting processes in a relatively short period of time, often alongside ongoing projects and with limited resources. For CFOs, legal and ESG officers, a step-by-step approach can help to tackle the issue in a structured manner without having to set up ESG reporting as an ad hoc project every year.
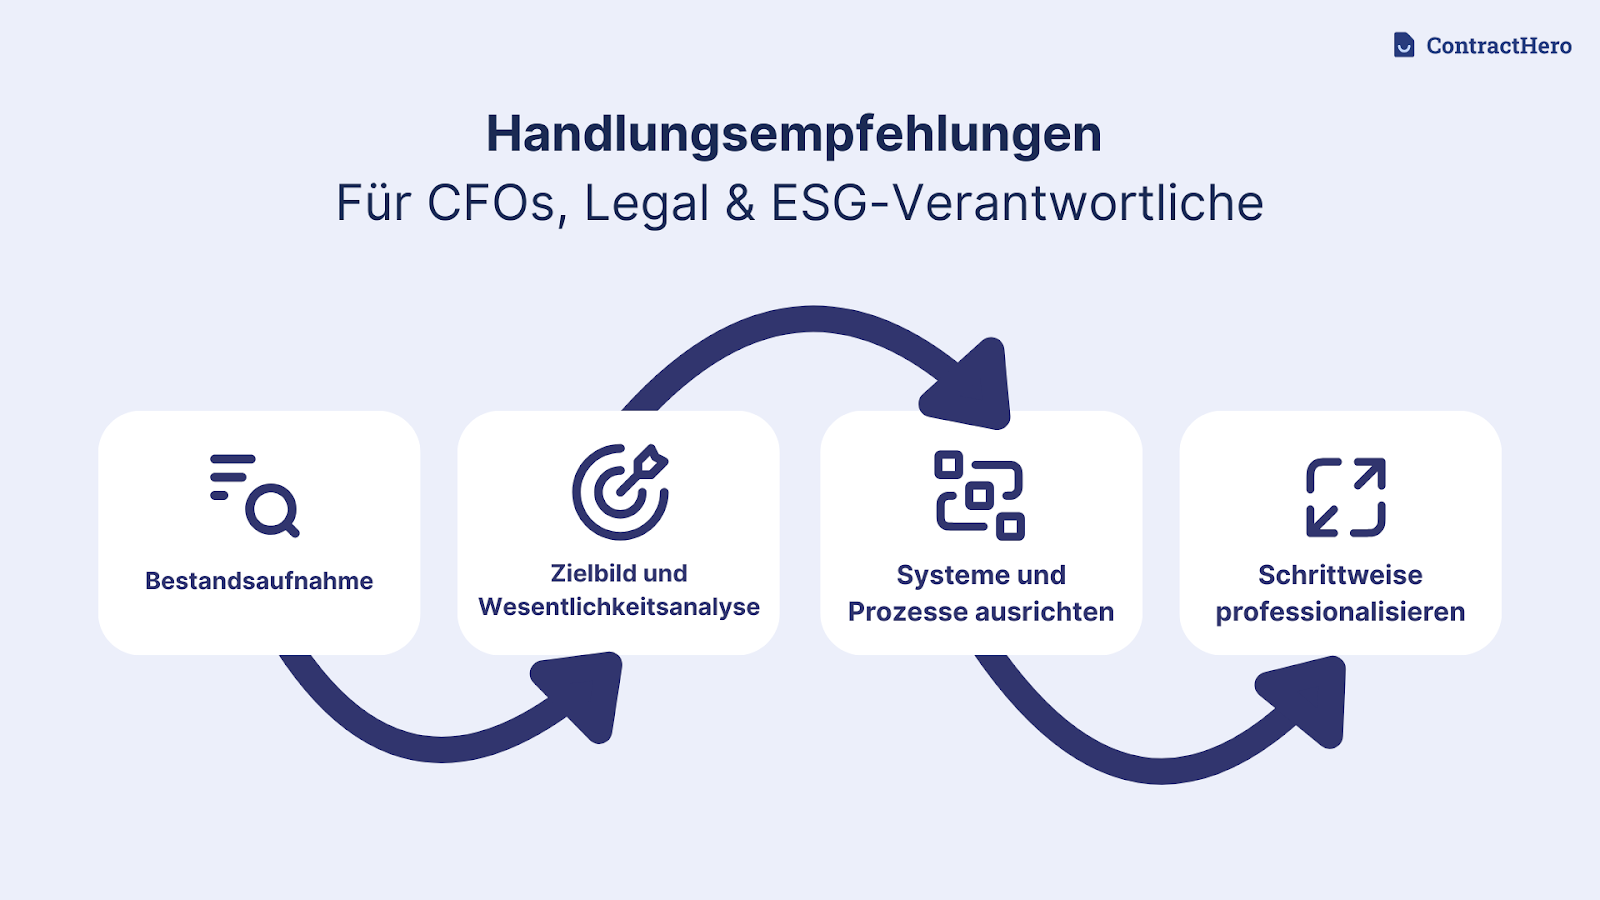
inventoryThe first step is to take an honest inventory. The first thing to do is to clarify which ESG reports already exist, for example, according to NFRD, at customer request, or in the form of voluntary sustainability reports. At the same time, you should systematically record where relevant contracts, policies, and certificates are located today and which data can already be used. This will reveal which foundations are available in the short term and where gaps need to be closed.
Target vision and materiality analysis
The next step is to define a clear target vision. Which ESG issues are truly material to the business model – in terms of environmental, social, and governance factors? A structured materiality analysis helps to prioritize the multitude of possible issues and focus on those that have the greatest impact on stakeholders and the company. At the same time, the potential financial implications of not addressing key ESG issues should be assessed. These include higher capital costs, stricter lending conditions, or exclusion from supply chains.
Aligning Systems and Processes
Building on this, systems and processes should be aligned so that ESG reporting does not have to be restarted every year as a one-time, large-scale effort. Contract Management ESG tools and financial systems should be interconnected—for example, via APIs—so that data can be reused. Clear governance is just as important: there needs to be a coordinated set of roles and responsibilities.
Gradual Professionalization
Ultimately, the goal is not to try to fully resolve the issue all at once, but rather to build up and professionalize ESG reporting and Contract Management step by step. A practical approach involves establishing a robust minimum set of metrics and processes that operate reliably and are well documented. This serves as a foundation: As experience grows, the scope and depth of ESG reporting can be expanded and more closely integrated with financial management. It is precisely then that the added value of a seamless interplay between Contract Management, ESG reporting, and finance becomes apparent.
Conclusion: " Contract Management " as a Foundation for Robust ESG Reporting
ESG reporting is now a central component of sustainability reporting and has become mandatory for many European companies under the Corporate Sustainability Reporting Directive (CSRD) and the ESRS. At the same time, practice shows that without looking at contracts, ESG reporting often remains incomplete. Supplier, energy, IT, and financing contracts regulate energy consumption, social standards, governance requirements, and disclosure obligations. Those who do not record this information in a structured manner run the risk of integrating important data into their reports only with great effort or not at all.
A modern “ Contract Management ” provides the necessary foundation here. It helps systematically capture ESG-related clauses and obligations in the contract portfolio, assign responsibilities, and keep track of deadlines . This reduces risks, avoids duplication of effort, and aligns ESG reporting more closely with the actual agreements—rather than having to search through individual PDFs, emails, and folder structures all over again every year.
ContractHero supports companies in precisely this area. The platform centralizes contracts, makes ESG-relevant content easier to find, and enables important information to be displayed using fields, filters, and reminders. ESG teams, finance, legal, and procurement can thus work more closely together and incorporate contract data into their reporting in a targeted manner. ESG reporting thus becomes less of a mere obligation and more of an integral part of structured, future-oriented sustainability and corporate governance.